Posts

Is this India's Sub-prime moment?

Ever since the IL&FS crisis hit the Indian markets in Sep'18, several things have changed for the NBFCs (Non-Banking Finance Companies), Banks and investors in debt mutual funds. This blog looks at the core problem and resulting implications for retail investors! Background NBFCs are non-deposit taking organizations that are known to reach channels not easily accessible by banks for lending. NBFCs primarily takes loans from banks and instituitional investors such as Mutual Funds & Insurance companies at say 10% and lends it to businesses such as MSMEs, Real estate builders etc at say 14%. They make 4% (14% - 10%) of the entire loan disbursed, provided such loan gets repaid. Similar to banks, unpaid loans get classified as NPAs (Non-Performing Asset). NBFCs must also set aside money from their profits to cater to such NPAs (called Provisioning). The Stats Per RBI, as of Mar'18, total bank deposits in the country stood at Rs.117Tn (Lac crores), with NPAs of Rs.10Tn. In c...
Planning your Family Budget

Image
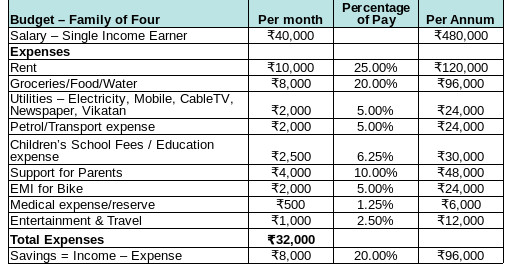
New year is here - while national budget is being prepared with a lot of vigor in the election year to impress voters, we have the responsibility to prepare a budget for our homes. Some of us may wonder if budgeting is of any use at all as most of our income anyway gets spent every month. This may be true in the initial income earning phase, when our incomes are lower but as we progress in our lives and career, annual planning of home budget greatly helps provide a disciplined approach to track our expenses in a structured manner. A Sample home budget Let us help Bharath, age 34, an administrative executive, prepare his annual home budget for 2019. He lives in a rented house with his wife and two children aged 5 & 3. His monthly take home pay is Rs.40,000 and he is a single income earner for his family. Bharath’s primary expense comprises his rent of Rs.10,000 and he spends another Rs.8,000 on food. His utilities and petrol/transport expenses comes to Rs.4,000....

Investment Triangle - Discipline & Time

Knowledge, Discipline & Time are the 3 vertices of an investment triangle. In this issue, we are going to examine the next 2 vertices of the investment triangle – Discipline & Time. Discipline is easy when imposed Discipline in investing is an essential ingredient to successful investing. When we stay invested in a right asset over a longer duration, it certainly pays off. Let us take Suresh, a teacher, who has a home loan EMI to pay for 15 years. Only if he pays his monthly EMIs regularly without fail, he could own the property at the end of the loan tenure. Paying a monthly EMI is a huge commitment and requires discipline on part of the investor. Similarly, take Sara, a lawyer, who pays the premium for her parent’s health insurance policy. Only if she pays the annual premium in a disciplined manner, her parents would be able to avail the hospitalization benefits. Most of us diligently pay our periodic payments in a disciplined way, like Suresh ...

Investment Triangle - Knowledge

Knowledge, Discipline & Time are the 3 vertices of an investment triangle. In this issue, we are going to examine the first area - Knowledge. Knowledge is foremost As investors, we need to be aware of the various financial products available in the market. Without first hand knowledge of various products, it is easy to fall prey to quick sales tricks and part our money to unsuitable products. Let us take the case of Anand, a manager in a private sector firm. In 2017, when he received his bonus, his relationship manager called him and recommended him to invest in Arbitrage funds (AF). The primary reason cited to him being good returns and no long term tax since arbitrage fund is treated at par with equity funds. It was further explained to him that a portion of the arbitrage funds would be invested in derivatives to cover any fall in stocks held by the fund. Anand was convinced and invested his entire bonus in one such arbitrage fund. However, Anand is very disappo...

How to increase Savings when Income is constant? -Part II

In the last issue, we explored 4 major leakages, which if prevented, could go a long way in saving your hard earned money. In this article, we are going to see 4 smaller but recurring leakages, which if left unnoticed, could deprive you of a significant contribution to your long term wealth. Leak 5 – Tax outgo EPF/PPF, children’s education fees & any home loan principal you pay takes care of your income tax rebate in section 80c. However, for those in the middle years of their career, who have completed their EMI liabilities, you may wonder if there are avenues beyond section 80c to save tax. This requires a fundamental shift in viewing assets as cash (or) capital assets. Cash assets such as bank FDs are draining on tax, so you may consider switching a part of them to tax efficient capital assets such as debt funds to plug the tax leakage. Lets say Guru has Rs.25Lacs in bank Fds and he falls in the 30% income tax bracket. At 7% interest, he earns Rs.1.75Lacs on whi...

How to increase Savings when Income is constant? - Part I

Image
So far we have seen how to measure the combined returns of one’s asset mix, called the portfolio, understand the difference between nominal & real returns and took a further step to examine the 3 different types in which assets are classified. In this issue, we are going to look at increasing your savings, while keeping income constant, by plugging the leaks on the expenditure side. Income – Savings = Expenditure Most of you may be familiar with this arithmetic, “Income – Expenditure = Savings”. The problem with this math is expenses being variable, savings too becomes variable. This is not good for your financial health in the long run. So, it is important to first select a certain fixed percentage (10% or 30%) of your income as savings and then spend the balance. Leak 1 – Insurance policies Insurance is required only to compensate you for any loss, other than term & medical policy, rest are not required for an individual. Insurance is not an investment, ther...

Movables (vs) Immovables

In this third classification of assets, we are going to understand assets based on whether they could be quickly converted to cash, a parameter more commonly known as liquidity. It is a key characteristic that ties an investor’s preference to a particular asset class. Assets that can be easily converted to cash form Movables and the rest form immovable assets. Movable Assets Most of the cash assets such as bank FD, RD & Post office schemes and capital market instruments such as open-ended mutual funds & stocks are liquid and form part of movable assets. There are 2 stages in one’s life when most people desire to have a higher percentage of the movable assets in their portfolio. They are: - Buying a dream home - Children’s Education/Marriage Lets take Robin who is building his dream home. Due to an unexpected rise in the cost of certain raw materials, say his budget overshoots by 20%. He now needs extra cash to meet this shortfall. Even if he has other properties...